Home loans built around you
Your journey home begins here.
Colibri Home Loans is your Trusted Guide on a better path to homeownership. We do things differently—we listen, find solutions built around you, and save you money along the way.
Serving TX, FL, TN, ME, SC, and NC
Clarity Changes Everything
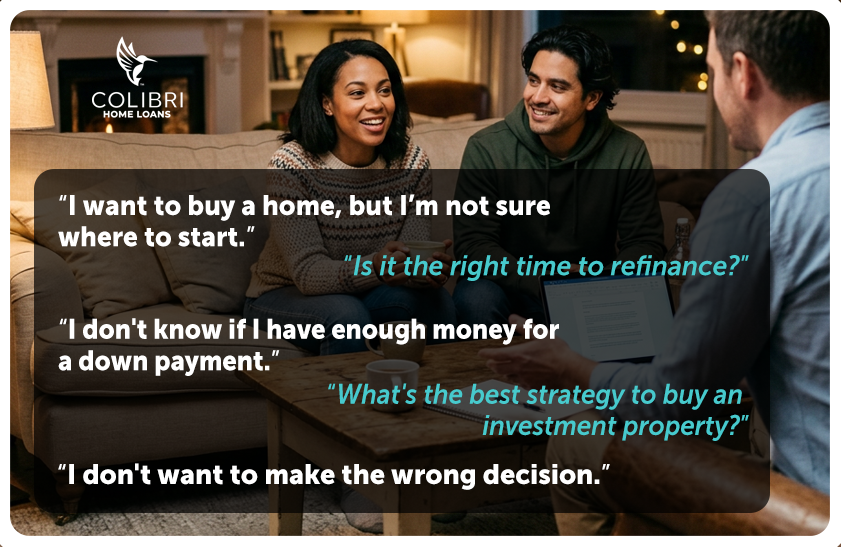
Questions are the starting point, not a roadblock.
Buying a home or investment property can feel intimidating. Can I afford to buy? Do I qualify for the right loan program? Uncertainties don’t have to hold you back. Colibri Home Loans helps you understand what’s possible, explore your options, and build a clear strategy for moving forward with confidence.
A Clear Path Home
Personal guidance for a better path Home.
You bring the goals. We’ll build the plan. We take the time to understand the full picture, anticipate potential obstacles, and create a personalized mortgage strategy—then guide you through every step from pre-approval to Welcome Home.
Verified client reviews
Real stories. Real results.
Read real experiences from our clients.
Meet the team
Experienced guidance with personal attention.
Colibri Home Loans combines expert lending knowledge with relationship-driven service.
Meet the Colibri team
What fuels us
It’s all about the joy of Homeownership.
Home loans are what we do. Helping people experience the joy of homeownership is why we do it.
We believe a home is more than a place—it’s where memories are made, families grow, and life happens. Our job is to make the loan process that gets you there as clear, smooth, and affordable as possible.
We’re not like other mortgage lenders. We listen, find solutions built around you, and look for every opportunity to save you money along the way.
Licensed in: Texas, Tennessee, Florida, Maine, South Carolina, and North Carolina.
More About ColibriLoan options
Financing shaped around real life.
Explore purchase, refinance, investor, and alternative-documentation options with a team that helps you compare the details clearly.
01
Conventional Home Loans
Flexible purchase and refinance financing for qualified borrowers.
Explore option → 02FHA Home Loans
Accessible down payment and qualification options for eligible buyers.
Explore option → 03VA Home Loans
Valuable financing benefits for eligible service members and veterans.
Explore option → 04First-Time Homebuyer Loans
Clear first-purchase planning, financing comparisons, and preparation.
Explore option → 05Down Payment Assistance
Explore eligible help with a down payment or closing costs.
Explore option → 06Non QM Loans
Flexible options for complex income, assets, and property scenarios.
Explore option → 07Bank Statement Loans
Alternative income documentation for qualifying self-employed borrowers.
Explore option → 08Jumbo Home Loans
Financing designed for loan amounts above conforming limits.
Explore option → 09Investment Property Financing
Purchase and refinance solutions for residential real estate investors.
Explore option → 10Refinance Home Loans
Explore payment, term, rate, and equity-access objectives.
Explore option → 11Cash-Out Refinance
Replace an existing mortgage while accessing available home equity.
Explore option → 12Renovation Loans
Finance an eligible purchase or refinance with planned improvements.
Explore option → 13USDA Home Loans
Zero-down-payment potential for eligible borrowers and properties.
Explore option → 141099 Mortgage Loans
Qualification paths designed around eligible 1099 income.
Explore option → 15DSCR Loans
Investor financing that may qualify using property cash flow.
Explore option → 16HELOC
A revolving line of credit secured by available home equity.
Explore option → 17Adjustable-Rate Mortgages
An initial fixed period followed by scheduled rate adjustments.
Explore option → 18Foreign National & ITIN Loans
Specialized financing for eligible non-citizen borrower scenarios.
Explore option → 19Self-Employed Home Loans
Documentation options that reflect how business owners earn income.
Explore option →Frequently asked questions
Straight answers for the decisions ahead.
Every situation is different. These answers offer a starting point; a Colibri consultation can make them specific to you.
Ask Us a QuestionWhat is a mortgage broker and why does it matter?
A mortgage broker helps compare loan options from multiple lending sources and guides you through qualification, documentation, and closing. That broader view can be especially useful when your goals or income do not fit a single standard path.
When do I lock my interest rate?
A rate lock is typically considered after you have an accepted contract and a lender-ready loan file. Timing depends on your closing date, program, market conditions, and lock period, so your loan officer should explain the tradeoffs before you decide.
How do I qualify for a mortgage?
Qualification considers income or eligible assets, credit, current debts, down payment, property details, and the specific loan program. A complete review is more reliable than any single rule of thumb.
What is the difference between pre-qualification and pre-approval?
Pre-qualification is often an early estimate based on information you provide. Pre-approval generally includes a more detailed review of credit, income, assets, and documents, making it more useful when you are ready to shop seriously.
What is mortgage refinancing?
Refinancing replaces an existing mortgage with a new loan. Common goals include changing the rate or term, reducing a payment, removing mortgage insurance, or accessing equity, but costs and long-term impact should be compared carefully.
How do I qualify for a VA loan?
VA eligibility generally requires qualifying military service and a valid Certificate of Eligibility. The borrower, property, occupancy, credit, income, and residual-income guidelines also apply.
What is a jumbo loan, and when might I need one?
A jumbo loan finances an amount above the applicable conforming loan limit. It may be used for higher-value properties and often has more detailed credit, reserve, income, and appraisal requirements.
I am self-employed. Can I still get a mortgage?
Yes. Depending on the program, qualification may use tax returns, business and personal bank statements, 1099 income, profit-and-loss information, or other eligible documentation.
What is the difference between a HELOC and a cash-out refinance?
A HELOC is a revolving second-lien credit line, while a cash-out refinance replaces the existing first mortgage with a larger loan. The best fit depends on rates, payment structure, closing costs, equity goals, and how you plan to use the funds.
How does investment property financing work?
Investor financing may qualify through conventional income, property cash flow, or other program-specific methods. Down payment, reserves, lease or rent analysis, property type, and the number of financed properties can all matter.
What are the benefits of a USDA loan?
Eligible USDA loans may offer zero-down-payment financing and competitive terms for qualifying borrowers purchasing an eligible property in an approved area. Household income and occupancy requirements apply.
How does an adjustable-rate mortgage work?
An adjustable-rate mortgage has an initial fixed-rate period followed by rate adjustments based on an index, margin, and adjustment caps. It can be useful in the right timeline, but future payment changes should be understood up front.
What is an asset based mortgage?
An asset based mortgage may use eligible liquid assets, investments, or retirement funds to help document an ability to repay. The exact calculation, eligible account types, seasoning, and reserve requirements vary by program.
How do I get started with the loan process?
Begin with a conversation about your goals, timing, property, income, assets, and credit. Your loan officer can then outline useful documents, possible programs, and the most practical next step.